
Revenue Recognition in the Manufacturing Industry - An Industry Supplement
Revenue recognition under ASC 606 can be complex for manufacturers. Make sure you get it right using this supplement to BDO's "Blueprint" on ASC 606.
BY ACCESSING THE FASB DOCUMENTS ON THIS SITE, YOU ACCEPT AND AGREE TO THESE FASB TERMS AND THE WEBSITE TERMS AS APPLIED TO YOUR USE OF THIS SITE OR ANY FASB LICENSED DOCUMENTS.
Overview
A manufacturing entity applies ASC 606, Revenue from Contracts with Customers, to recognize revenue from a contract with a customer. ASC 606 includes a detailed five-step revenue recognition model which requires a manufacturer to identify its performance obligations in a contract with a customer and recognize revenue when or as its performance obligations are satisfied.
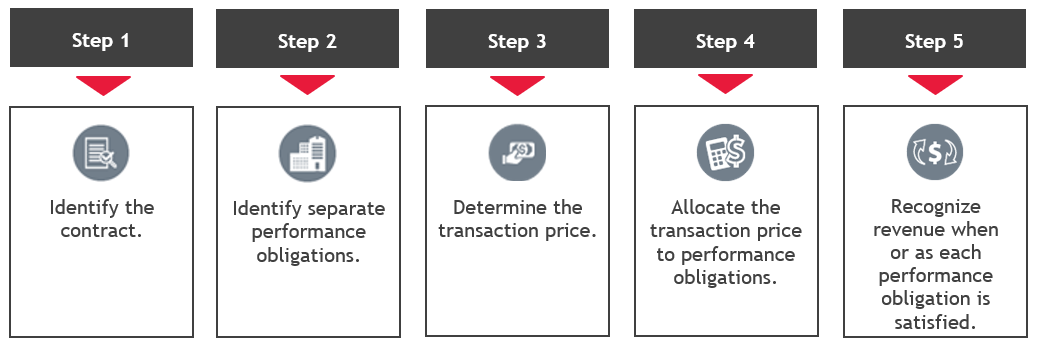
Manufacturing entities face unique challenges in applying certain aspects of the guidance because of the judgments inherent in applying the guidance and unique nature of manufacturing arrangements.
Supplement to our Blueprint
This publication discusses certain significant revenue recognition considerations specific to the manufacturing industry in applying the five-step revenue recognition model. We encourage you to read the interpretations and examples in this publication with our Blueprint, Revenue Recognition Under ASC 606, which includes a detailed discussion of the five-step revenue recognition model and certain other key concepts included in ASC 606.